CNA Financial reports earnings as insurance pricing pressures mount
CNA Financial is set to report quarterly earnings as the insurer faces mounting pressure on pricing across its commercial lines.
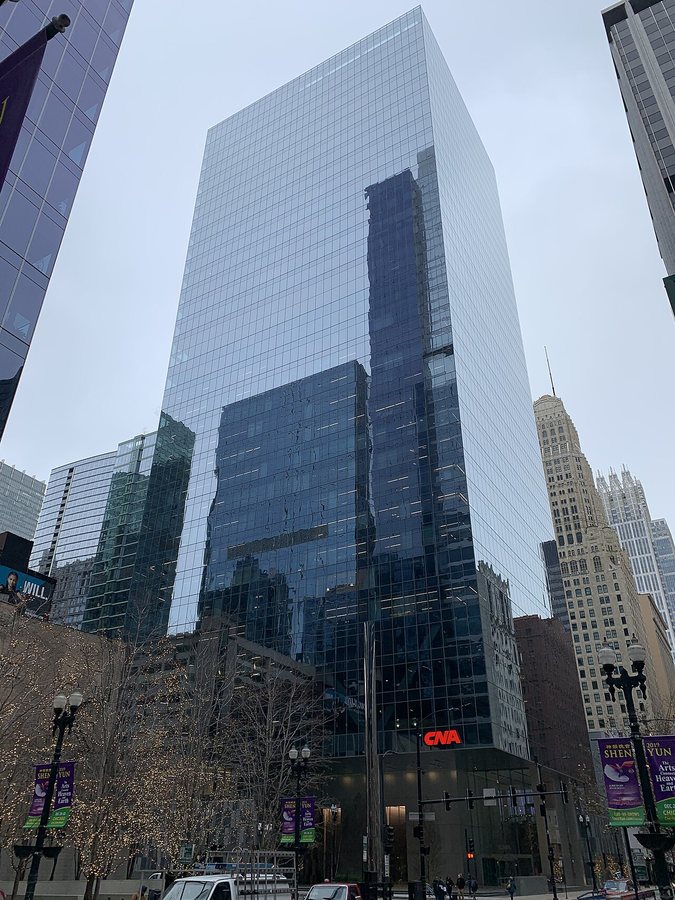
CNA Financial, one of the largest commercial property and casualty insurers in the United States, is scheduled to report its latest quarterly earnings as pricing pressures in the insurance market continue to build. Investors are watching closely to see how the company is balancing premium growth against rising claims costs and competitive conditions.
The insurance industry has spent much of the past few years adjusting to a difficult environment. Higher losses from severe weather, inflation in repair and replacement costs, and large jury verdicts have pushed carriers to raise rates on many commercial policies. At the same time, some competitors have been willing to accept thinner margins to win business, which can make it harder for established insurers to pass along increases without losing customers.
For CNA, the earnings release is an opportunity to show whether its underwriting discipline is holding up. Analysts typically focus on the combined ratio, a key measure of profitability that compares losses and expenses to premiums earned, along with trends in premium growth and reserve development. Any sign that pricing gains are slowing relative to loss trends would likely draw particular attention from the market.
The outcome matters beyond the company's own shareholders. Commercial insurance pricing affects businesses of all sizes, from small contractors and restaurants to large manufacturers and healthcare providers, many of which have reported higher premiums in recent renewal cycles. How CNA describes its pricing outlook could offer a signal about whether relief for those policyholders is likely soon or whether elevated costs will persist.
Market observers will also be listening for commentary on capital management and investment income, areas that can offset underwriting pressures. Rising interest rates have lifted returns on the bond portfolios held by insurers, but they have also affected the value of existing holdings, making the balance between those forces a recurring theme in recent industry results.
6