Luxury Brands Face Structural Crisis as Growth Model Hits Limits
Luxury giants like LVMH, Hermès, and Estée Lauder are losing momentum as a decades-old growth playbook built on mass marketing and artificial scarcity runs out of road, according to a new analysis that urges a return to pre-1990s practices.
Luxury brands are confronting a structural crisis rather than a cyclical downturn, as the growth model that powered three decades of expansion now undermines the very qualities that made them desirable. The warning comes as several of the sector's biggest names have seen sharp declines in valuation and consumer reach.
LVMH, the conglomerate behind Givenchy and Guerlain, briefly became Europe's most valuable company in April 2023. Since then, most luxury giants have lost momentum. Estée Lauder's stock price has shed 35% since the start of 2024, Hermès has lost 34% so far this year, and shares in Richemont, owner of Cartier and Chloé, have fallen 15% after fluctuating.
The core problem, according to the analysis, is that the contemporary luxury model has run out of road. Brands increasingly lean on heritage and iconic products instead of creating the next generation of desirable goods. The Hermès Birkin bag, for instance, was created in 1984. In 2023, Bernstein estimated that the Birkin, the Kelly bag from 1977, and a rebrand of a bag invented in the 1930s accounted for more than 13% of the brand's annual revenue.
A reputational recession has compounded the innovation slump. Post-COVID price increases far outpaced any gain in functional value, and the sector lost 70 million consumers between 2022 and 2025, according to a Bain estimate. Meanwhile, the super wealthy are increasingly drawn to one-of-a-kind experiences, such as a house on a pristine coast, that reduce other billionaires' ability to buy them, rather than to artificially rare luxury products.
Technological disruption is accelerating as well. In automobiles, innovative Chinese players like NIO and Yangwang are redefining what premium products look like and what experiences mean, already challenging the likes of Lamborghini and Mercedes-Benz in China.
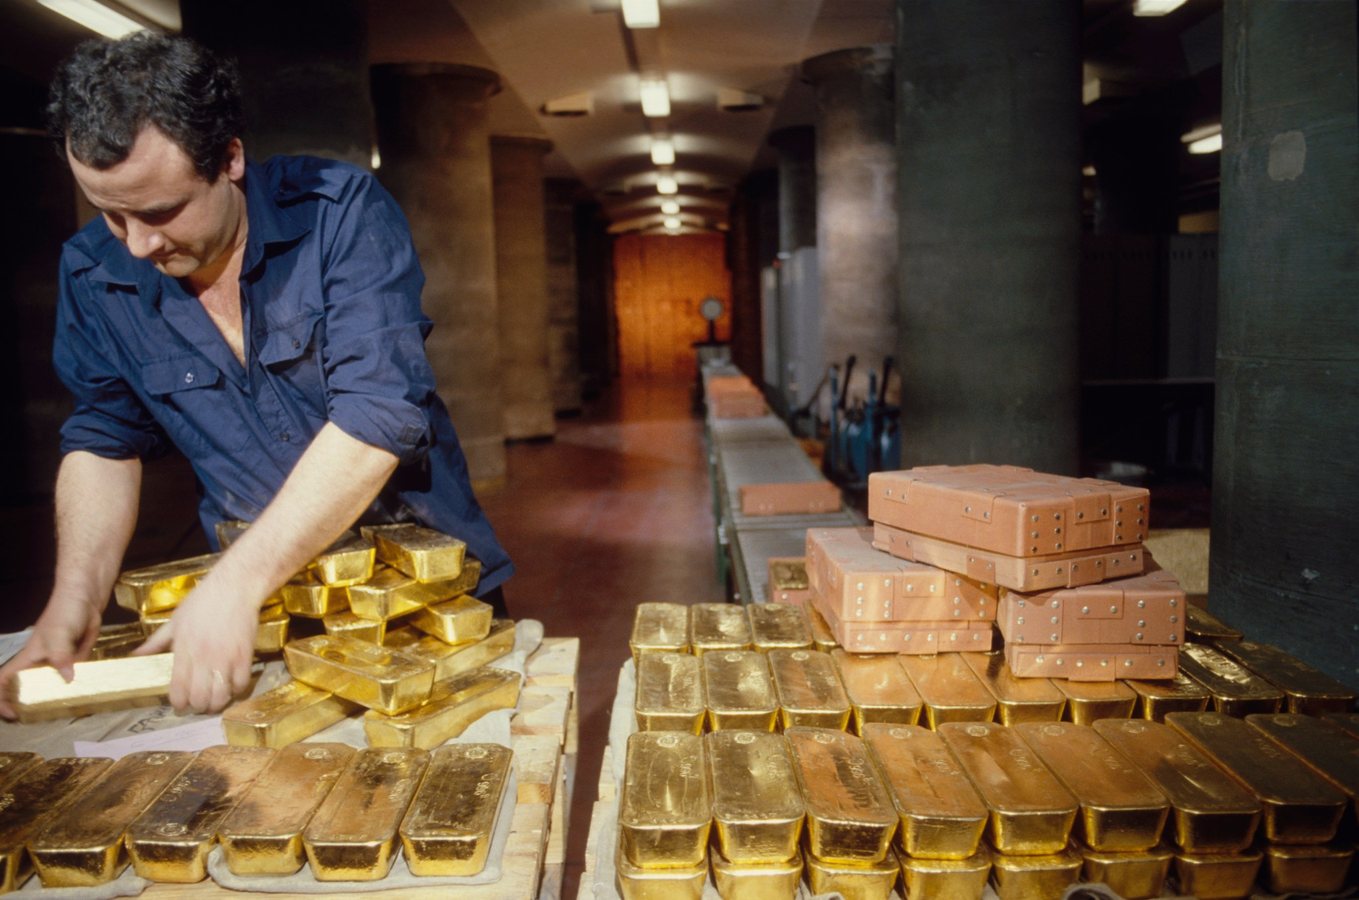
Most fundamentally, luxury has become a commodity. Since the ascent of LVMH in the early 1990s, the industry has followed a common playbook built on mass-marketing intensity, standardized retail experiences, global scale, and industrialized, sometimes offshored, supply chains. Brands increasingly hide abundance behind stories of scarcity even as they emphasize craftsmanship in their communication.
The paradox is stark: the world has never counted so many billionaires, yet the number of historic fashion houses showing haute couture in Paris had dwindled to three this past July, out of the eight present in 1990 and still alive today. Houses that once sold style now sell logos, and houses that once produced two collections a year now produce six. In the pursuit of growth, luxury has become less rare, resulting in a loss of creativity, differentiation, and internal dynamism.
Talent is feeling the strain. In March this year, Jing Daily reported that luxury brands are hemorrhaging employees because staff no longer see where they can contribute beyond optimizing a model that has reached its limits. A culture of perfection, the analysis argues, trumps one of excellence.
Luxury's expansion has also carried environmental and social costs. Growth has been accompanied by rising emissions, resource consumption, biodiversity loss, and supply chain controversies. Most luxury companies have made genuine ESG progress, and an overwhelming majority of the largest are on track to become carbon neutral by 2030 on scope 1 and scope 2 emissions. But on scope 3, which accounts for 95% of their emissions from supply chains and customers, only four of the largest 18 companies have set absolute reduction targets and are on track to achieve them.
Research shows only 25% of the top 100 companies have a chief sustainability officer in the top management team, and brands continue to invest three times as much in marketing and selling as in innovation for sustainability. Sustainability remains largely a compliance and reputational exercise rather than a source of strategic innovation, even as consumers and societies increasingly question business models built around excess and inequality.
The proposed solution is not a better version of today's model but a different one that returns to pre-1990 practices and invents new ones for the twenty-first century. Brands should produce more on demand and less for stock, an approach once applied across the board. Artificial intelligence can dramatically improve forecasting, reducing waste while restoring genuine scarcity. Luxury should also return to selling more wearable and glamorous products, the analysis concludes.
8